
In 2023, the Global Third-Party Logistics (3PL) Market experienced a downturn as rates and demand declined worldwide due to economic challenges and geopolitical instability. Revenue for global 3PL services fell significantly, primarily driven by weakness in International Transportation Management (ITM) and Transportation Management (TM). Falling transportation rates exacerbated declines in logistics costs (spend) and in 3PL revenues. After a 21.6% drop in 3PL revenue for 2023, the global 3PL market began to stabilize throughout 2024. Armstrong & Associates, Inc. (A&A) estimates that the Global 3PL Market grew by 2.4% to $1.21 trillion in 2024, with an anticipated 5% growth in 2025, bringing it to $1.27 trillion.
Furthermore, A&A estimates that global logistics spending decreased by 1.5% in 2023, dropping to $11.5 trillion. With ongoing geopolitical tensions and uncertainties around tariffs and trade, global logistics spending is projected to grow by 5.2% to approximately $12.6 trillion in 2025.
The global 3PL market is highly fragmented and underpenetrated, with abundant growth potential. Tariff uncertainty, trade policy changes, the COVID-19 pandemic, and other unprecedented supply chain disruptions in the Red Sea and the Panama Canal in recent years have accelerated the pace of outsourcing in global logistics.
3PL customers realized that supply chains need to be more flexible, and it’s more beneficial to source products and components from multiple countries than just one. This uncertainty presents opportunities for Third-Party Logistics Providers (3PLs) to become strategic partners and offer valuable services while 3PL customers seek to mitigate risks. In addition, 3PLs help their customers save costs and offer specialized services, including expertise in international transportation management, warehousing, and distribution. The global logistics market remains a significant opportunity for 3PLs. Global 3PL revenue in 2024 was 10.1% of total logistics spending, a slight increase from the 10% 3PL penetration rate in 2019. We expect the global 3PL revenue penetration rate to remain stable between 2025 and 2026. A&A estimates global 3PL revenues will continue to grow, with 2026 expected to see a 4.9% increase to $1.35 trillion.
Global Logistics Costs & 3PL Revenues

A&A’s Global 3PL Market estimates are comprised of three major industry segments:
- International Transportation Management (ITM): Third-party logistics providers offering international air and ocean transportation management services, typically managed under contracts. These services often include freight forwarding, warehousing, container freight station operations, trade compliance, customs brokerage, and inland shipment management.
- Value-Added Warehousing and Distribution (VAWD): Third-party logistics providers offering long-term contract warehousing and distribution center management, and various value-added services. These contracts typically have terms ranging from 1 to 3 years, with some extending up to 10 years or more. VAWD does not include short-term “Public” warehousing.
- Transportation Management (TM) comprising Domestic Transportation Management (DTM) and Dedicated Contract Carriage (DCC):
- DTM: Third-party logistics providers offering non-asset-based transportation management services, primarily focused on shipments originating from and destined for locations in North America. These services are typically performed with freight brokerage and are governed mainly by contracts. The DTM sub-segments include Freight Brokerage, Intermodal, Managed Transportation, and Last-Mile Delivery.
- DCC: Third-party logistics providers offering dedicated contract carriage services to customers through agreements typically having one to seven-year terms. DCC operations primarily focus on managing asset-based truckload transportation. 3PLs supply drivers, transportation equipment, and management personnel as part of this service.
VAWD is the only 3PL segment to have posted positive growth in 2023, surpassing the ITM segment in revenue for the first time. The size of the global VAWD 3PL segment in 2024 was $310.6 billion, representing a stable Year-Over-Year (YOY) increase of 1.8% and a 31.7% increase over 2019, when the segment’s gross revenue was $235.9 billion. The global VAWD market is expected to grow 2.5% in 2025, reaching $318.4 billion.
The most significant impact currently stems from tariff and trade-war uncertainties, despite ongoing challenges such as port closures, container shortages, labor shortages, natural disasters, geopolitical conflicts, regulatory compliance issues, and rising transportation costs in the global ITM 3PL segment. Ports and imports saw a significant increase in cargo volumes before the tariffs were in place. This was mainly driven by retailers moving cargo ahead of the Trump administration’s expected increase in duties on goods from China, Mexico, and Canada. It is estimated that global ITM increased by 7.4% to $298.6 billion in 2024 and will lead all 3PL segments, growing by 12.2% to $335.1 billion in 2025.
When analyzing 3PL market segments globally, we combine Dedicated Contract Carriage (DCC) and Domestic Transportation Management (DTM) into a single ground/road transportation management segment dubbed “Transportation Management” (TM) since DCC is a more defined contractual form of trucking and is less common in some geographies. The global TM 3PL segment experienced a slight YOY increase in gross revenue of 0.3% to $583.3 billion in 2024, following a 14.6% decrease to $581.8 billion in 2023. With less restrictive monetary policy, increased demand, and a return to normalized rates in 2025, the global TM 3PL segment will grow by 2.6% to $598.3 billion.
Global 3PL Revenues – Total and by 3PL Segment

*Greater China: China, Hong Kong SAR, Macao SAR, Taiwan SAR
**ASEAN includes Brunei Darussalam, Myanmar (Burma), Lao P.D.R., Cambodia, Vietnam, Thailand, Singapore, Philippines, Malaysia, and Indonesia.
As the region with the most 3PL revenue globally, Asia Pacific has posted a 4.9% CAGR from 2016 to 2024 and is anticipated to grow at a 7.5% CAGR over the next two years. Major 3PLs based in the region include Nippon Express, Sinotrans, and KLN (formerly Kerry Logistics Networks). A&A’s list of the 25 largest Asia-based 3PLs based on 2024 3PL gross revenue is as follows.
Top 25 Asia-Based 3PLs
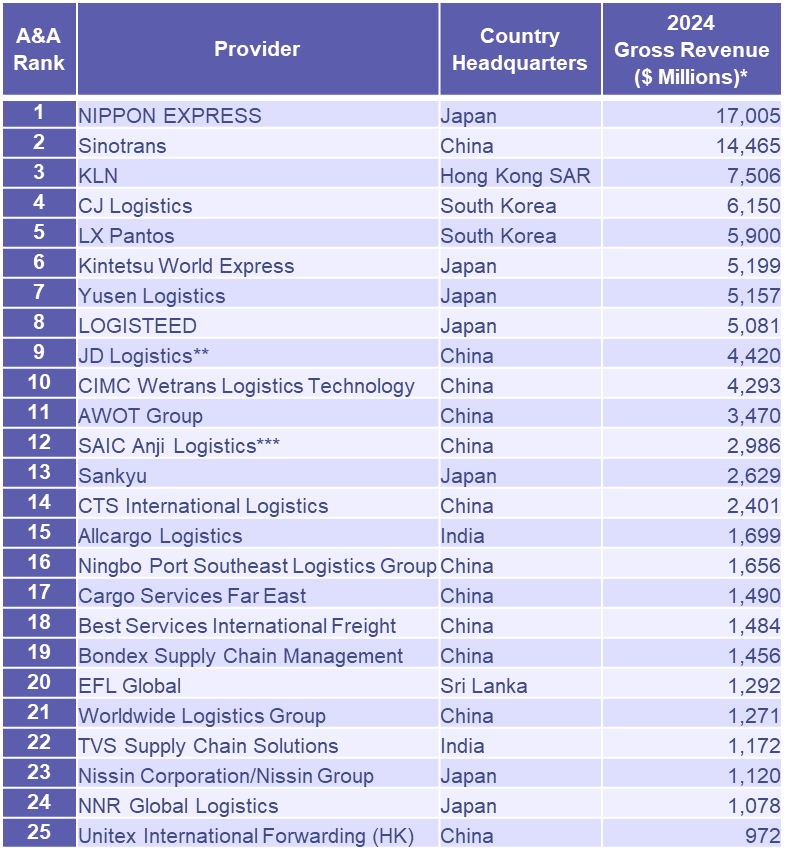
*Revenues cover all four 3PL Segments (DTM, ITM, DCC, and VAWD), are company-reported or A&A estimates, and have been converted to US$ using the exchange rate on December 31, 2024.
**Only includes Supply Chain (VAWD) revenue.
***In-house logistics revenues were capped at 50% for fairness.
On May 12, Armstrong & Associates (A&A), in partnership with The Logistics & Supply Chain Management Society and CargoNow, will host its annual 3PL Value Creation Asia Summit in Singapore.
The Summit brings together senior executives from 3PLs, investment community leaders, and technology innovators to network and share cutting-edge ideas for achieving growth in 2026 and beyond.
This unique event offers an in-depth exploration of the operational, financial, and technological aspects of the global 3PL industry.
As part of this year’s 3PL Value Creation Asia Summit, A&A will present its exclusive Top 50 Asia-based 3PLs list, recognizing leading logistics providers across the region.
Key panel discussions at this year’s summit, revealing A&A’s Top 50 Asia-based 3PLs, latest marketing sizing estimates, and 3PL market trends and insights across Asia and globally, include “Third-Party Logistics (3PL) Market Trends and Analysis,” “Global and Regional 3PL Market Trends,” and “Tariff Impacts and Global Trade Dynamics.”
For more information about this event or to join us as an attendee, speaker, or sponsor, please visit: https://www.3plogistics.com/3pl-value-creation-asia-summit-2026/.
About the author
Evan Armstrong
Chief Executive Officer · Armstrong & Associates